Seb Frey is a REALTOR® and founder of Team Sixty Plus, a curated network connecting older adults and their families with trusted professionals across California. With decades of experience helping homeowners 60+ navigate major life transitions—like downsizing, aging in place, or passing on a legacy—Seb brings deep market knowledge, a compassionate approach, and a commitment to simplifying complex decisions. When he’s not advising clients, he’s sharing expert insights on real estate, retirement strategies, and quality-of-life resources for the 60+ community.
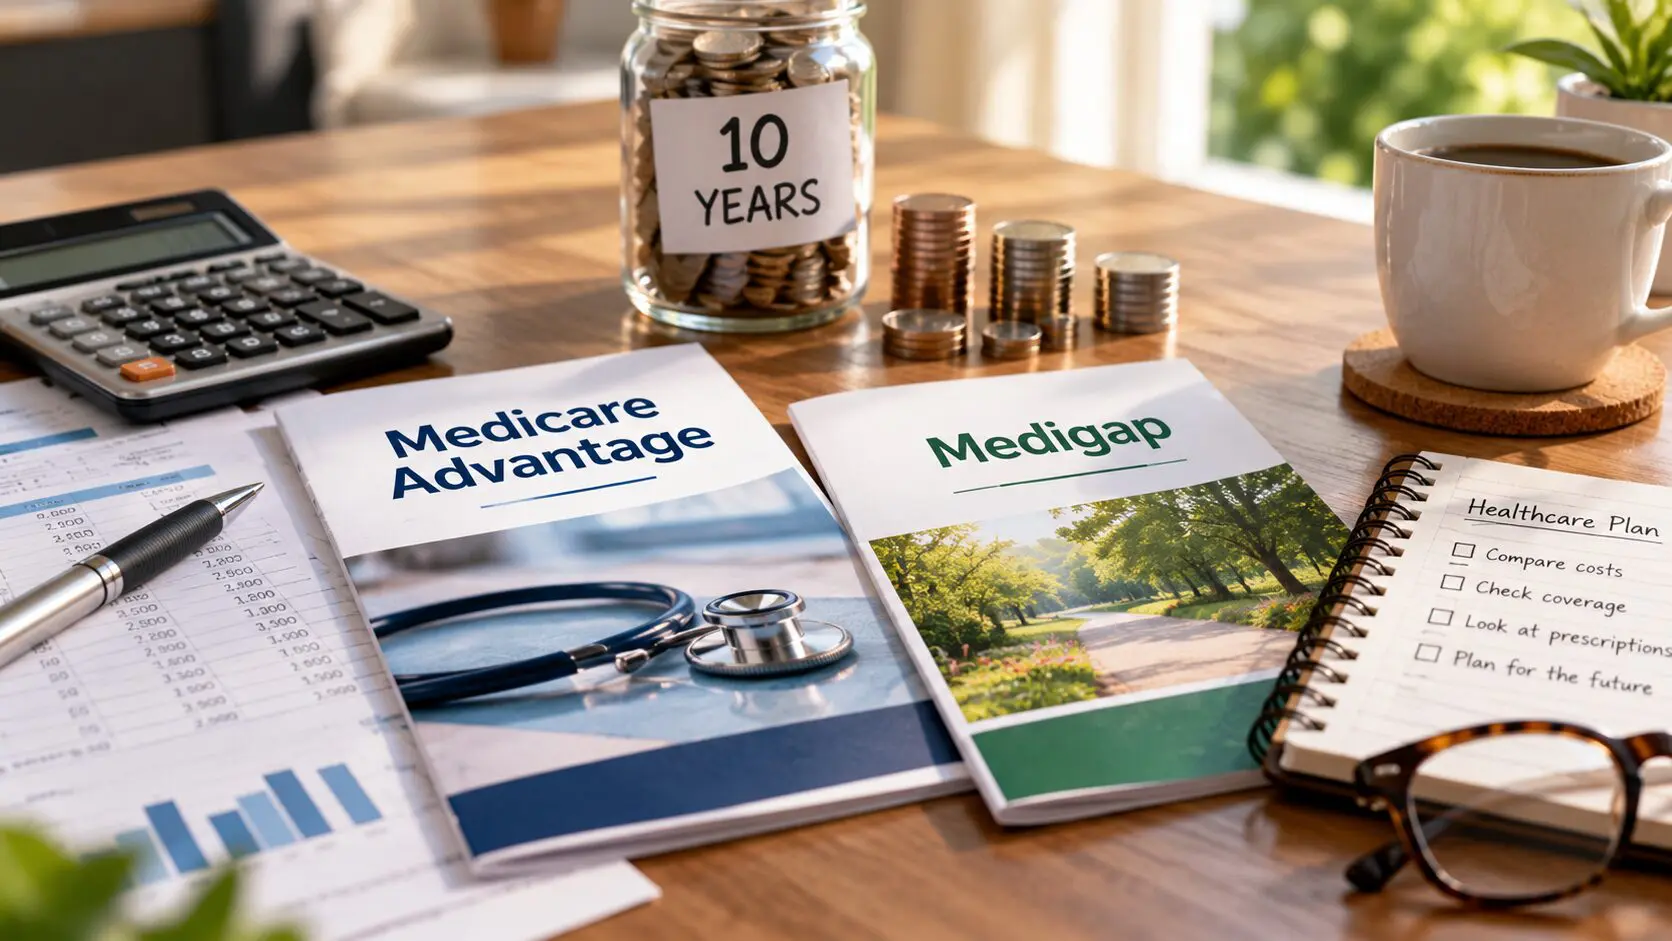
Every fall, the TV ads start: smiling retirees, a celebrity spokesperson, and a promise of “$0 premium plans with extra benefits you may be missing,” while your mailbox fills with glossy brochures and your phone rings with numbers you don’t recognize. Here’s what most of those ads won’t tell you: the choice between Medicare Advantage vs. Medigap is not really a health insurance decision. It’s a cash flow decision, a bet on your future health, your future income, and how much financial risk you’re willing to carry for the next 20 or 30 years.
Choose well, and you protect your retirement savings from the single biggest wildcard most retirees face: medical bills. Choose poorly, and you could lock yourself into a plan that looks cheap at 65 but gets expensive right when you can least afford it. Medicare Open Enrollment runs from October 15 through December 7, 2026, with new coverage starting January 1, 2027, so this is the window to get it right. Let’s skip the sales pitch and look at what each option really costs over 10 years.
The Quick Answer (For People Who Hate Long Articles)
- Medigap (Medicare Supplement) costs more every month, but your yearly medical bills become small and predictable. You can see any doctor in the country who takes Medicare. You pay for peace of mind.
- Medicare Advantage costs little or nothing every month, but you pay copays as you use care, you’re limited to a network, and a bad health year can cost you close to $10,000. You save on premiums by taking on risk.
- The catch nobody mentions: In most states, if you choose Medicare Advantage now and want to switch to Medigap later, an insurer can charge you more or turn you down because of your health. Your first decision matters more than you think.
Now let’s dig into the numbers.
Everyone Needs a Little Help Sometimes
There’s so much to know when it comes to lifestyle choices for Older Adults, it’s hard to know even where to begin. One way is to simply click on the button below and let one of our coaches give some guidance – at no cost to you.
Get Help NowFirst, a 60-Second Refresher on How Medicare Works
Original Medicare has two main parts. Part A covers hospital stays. Part B covers doctor visits, outpatient care, lab work, and medical equipment. Most people pay nothing for Part A, but everyone pays a Part B premium. In 2026 the standard Part B premium is $202.90 a month, and early projections put the 2027 premium at roughly $209.50. The official 2027 number is usually announced by CMS in November.
The problem with Original Medicare alone is that it has no ceiling. Part B generally pays 80% of approved costs, leaving you with the other 20%, with no annual limit. In 2026, a hospital stay also comes with a Part A deductible of $1,736 per benefit period. One cancer diagnosis, a heart procedure, or a long rehab stay can leave you with a bill in the tens of thousands.
That’s why almost nobody uses Original Medicare alone. You fill the gaps in one of two ways:
- Original Medicare + a Medigap policy + a Part D drug plan, or
- A Medicare Advantage plan (also called Part C), which replaces Original Medicare with a private insurance plan that usually includes drug coverage.
You keep paying your Part B premium either way. That cost is the same on both paths, so the real comparison is everything on top of it.
If you’d like a fuller walkthrough of each part before going further, Medicare Explained: A Quick Guide for 2026 breaks down Parts A, B, C, and D in plain English.
What Medigap Really Costs
Medigap plans are sold by private insurers but are standardized by the federal government. A “Plan G” from one company covers the exact same benefits as a Plan G from another. The only real differences are price and customer service. That makes shopping simple: find the lowest price from a stable company.
Plan G is now the most popular choice for new enrollees, since Plan F is no longer sold to people who became eligible for Medicare after January 1, 2020. With Plan G, after you pay the Part B deductible ($283 in 2026), Medicare-approved care is generally covered in full for the rest of the year. That includes hospital stays, surgeries, chemotherapy, and specialist visits.
The monthly premium
This is where Medigap hurts. According to a 2026 analysis by MoneyGeek, average Plan G premiums run about $196 a month at age 65 and about $262 a month at age 75 for “attained-age” policies. Prices vary a lot by state, ZIP code, gender, and whether you use tobacco.
Pay attention to how your policy is priced, because it changes what you’ll pay later:
- Attained-age pricing: Cheapest at 65, but the premium goes up as you get older. Most policies are sold this way.
- Issue-age pricing: Based on your age when you buy. It doesn’t rise just because you have birthdays, but it can still rise with inflation.
- Community-rated pricing: Everyone pays the same, regardless of age. More expensive at first, often cheaper in your 80s.
All three types also go up with medical inflation. A realistic budgeting assumption is that your Medigap premium will rise about 5% to 7% a year.
The budget-friendly version: High-Deductible Plan G
If the regular Plan G premium makes you wince, look at High-Deductible Plan G. You pay the first $2,950 of approved costs yourself (2026 figure), and then it works exactly like regular Plan G. Premiums are often a fraction of the standard version. For healthy retirees who keep an emergency fund, this can be one of the smartest money moves in all of Medicare.
Don’t forget Part D
Medigap doesn’t cover prescription drugs, so you’ll need a separate Part D plan. According to CMS projections for 2027, the average standalone Part D premium will be around $36 a month. The good news: thanks to the Part D out-of-pocket cap, your yearly drug spending is limited to $2,400 in 2027 (up from $2,100 in 2026). That cap applies whether you choose Medigap or Medicare Advantage.
What Medicare Advantage Really Costs
Medicare Advantage plans are private insurance plans approved by Medicare. They have grown fast: CMS projects about 34 million people, nearly half of everyone on Medicare, will be enrolled in 2027.
The monthly premium
This is the big selling point. CMS projects the average Medicare Advantage premium will drop to about $12 a month in 2027, down from about $14.37 in 2026. Many plans charge $0 on top of your Part B premium. Some even give part of your Part B premium back to you.
Most plans also include drug coverage plus extras that Original Medicare doesn’t offer, like dental cleanings, eyeglasses, hearing aids, gym memberships, or grocery allowances.
The costs you pay when you get care
Here’s the trade-off. Instead of paying a big premium up front, you pay as you go:
- Copays for doctor and specialist visits (often $0 to $50)
- Daily copays for hospital stays (often a few hundred dollars per day for the first several days)
- Coinsurance for expensive services like chemotherapy, dialysis, or imaging (often 20%)
- Copays for skilled nursing or rehab stays
The number that matters most: the out-of-pocket maximum
Every Medicare Advantage plan must have an annual out-of-pocket limit. For 2027, the federal maximum is $9,850 for in-network care and $14,800 combined for PPO plans that cover out-of-network care. Many plans set lower limits, so check yours. Research from KFF shows these limits vary widely from plan to plan.
Two important details: this limit resets every January 1, and it does not include your Part D drug costs, which have their own $2,400 cap.
The hidden costs that aren’t in dollars
Medicare Advantage also comes with rules that Medigap doesn’t have:
- Networks: HMOs generally only pay for in-network doctors and hospitals (except emergencies). PPOs cover out-of-network care, but at a higher cost.
- Prior authorization: Many services need plan approval before you get them. Denials and delays are a common complaint, and a federal Office of Inspector General review found some denied requests met Medicare’s coverage rules.
- Annual changes: Your plan’s doctors, drug list, and copays can change every year. Always read the Annual Notice of Change your plan sends each fall.
Medicare Made Simple
Medicare can be complicated – so let us break it down for you! Get our quick and easy guide, Medicare Made Simple!
Get the Guide!The 10-Year Showdown: Real Numbers
Let’s put both options side by side for a 65-year-old over 10 years. These are simplified illustrations, not quotes. Your actual costs will depend on your state, plan, and health. We’ll leave out the Part B premium (which you pay either way) and assume similar drug costs on both paths.
Medigap Plan G + Part D
- Plan G premium: starts at about $200/month ($2,400/year), rising 6% a year
- Part B deductible: about $300 a year
- Part D premium: about $36/month ($432/year)
10-year total: about $39,000. The key point is that this number barely changes whether you’re healthy as a horse or spend three years fighting a serious illness. You know your costs in advance.
Medicare Advantage with drug coverage ($0 premium)
This total depends entirely on your health:
| Your 10 years | Estimated out-of-pocket | vs. Medigap (~$39,000) |
|---|---|---|
| Healthy: 10 years of routine care (~$800/year) | ~$8,000 | Medicare Advantage saves ~$31,000 |
| Mostly healthy: 8 routine years + 2 years hitting the max | ~$26,000 | Medicare Advantage saves ~$13,000 |
| Average-to-rough: 7 routine years + 3 years hitting the max | ~$35,000 | About even |
| Chronic illness: 5 routine years + 5 years hitting the max | ~$53,000 | Medigap saves ~$14,000 |
| Serious ongoing illness: maxed out 8 of 10 years | ~$80,000 | Medigap saves ~$41,000 |
Assumes the in-network out-of-pocket maximum stays near $9,850. In reality, it tends to rise over time, which makes bad years more expensive.
What the numbers tell us
The break-even point is roughly three bad health years out of ten. If you have fewer than that, Medicare Advantage usually wins on cost. If you have more, Medigap usually wins.
But that’s not the whole story. Look at the shape of the costs, not just the total:
- With Medigap, your worst year looks almost the same as your best year: about $3,000 to $5,000 in premiums and small deductibles.
- With Medicare Advantage, your best year might cost $300 and your worst year close to $10,000 in medical costs alone, plus travel, time, and stress if you need care outside your network.
And here’s the uncomfortable truth: health problems tend to pile up as we age. The odds of having “bad years” in your late 70s and 80s are much higher than at 65. That’s exactly when switching to Medigap gets hardest.
Whichever path you choose, healthcare is only one line in your retirement budget. How to Stretch Your Retirement Income Without Sacrifice shows how to free up more monthly cash so a surprise medical bill doesn’t throw off your whole plan.
The Trap Nobody Warns You About: You May Not Be Able to Switch Back
This is the most important section of this article.
When you first sign up for Part B at 65 or older, you get a six-month Medigap Open Enrollment Period. During that window, any insurer must sell you any Medigap policy it offers, at the standard price, regardless of your health. No medical questions. No denials.
Once that window closes, the rules change. In most states, a Medigap insurer can ask health questions, charge you more, or reject you entirely if you have conditions like diabetes, heart disease, COPD, or a recent cancer diagnosis.
So picture this: you choose a $0 Medicare Advantage plan at 65 because you’re healthy. At 74, you’re diagnosed with a heart condition and want the freedom to see a top cardiologist outside your network. You try to switch to Medigap during Open Enrollment, and the application is denied. You’re stuck with Medicare Advantage.
There are a few exceptions worth knowing:
- Trial right: If you join a Medicare Advantage plan when you’re first eligible at 65, you generally have 12 months to change your mind and switch to Original Medicare with guaranteed access to Medigap. Medicare.gov explains these “trial rights” and other guaranteed-issue situations.
- States with extra protections: Connecticut, New York, Vermont, and Washington allow Medigap enrollment year-round with certain rules. About 15 states, including California, Illinois, Oregon, and Virginia, have a “birthday rule” or similar annual window that lets you switch between Medigap plans without health questions. The NAIC keeps a state-by-state chart. Note that many birthday rules only help you switch from one Medigap plan to another, not from Medicare Advantage back to Medigap.
- Losing your plan: If your Medicare Advantage plan leaves your area or you move out of its service area, you may get a guaranteed right to buy certain Medigap policies.
The bottom line: if you are leaning toward Medigap at all, the easiest and cheapest time to get it is when you first enroll. Choosing Medicare Advantage is easy to undo in a few cases, but it’s often a one-way door.
Who Should Choose Medigap?
Medigap usually makes more financial sense if you:
- Have savings to protect. If you’ve built a solid nest egg, Medigap is like an insurance policy on that money. You trade a known monthly cost for protection against big surprises.
- Already have chronic health conditions or a family history of serious illness, and you’re still in your guaranteed-issue window.
- Travel often or split time between states. Snowbirds love Medigap because any doctor in the U.S. who accepts Medicare will take it. Some Medigap plans also cover emergency care abroad.
- Want to choose your own specialists and hospitals, such as a top cancer center or academic medical center, without asking anyone’s permission.
- Hate surprise bills and paperwork. With Plan G, you rarely see a bill after the Part B deductible.
Who Should Choose Medicare Advantage?
Medicare Advantage can be a smart money move if you:
- Are on a tight monthly budget. If a $200+ monthly premium would squeeze your groceries or rent, a $0 premium plan keeps more cash in your pocket every month.
- Are healthy and have an emergency fund that could cover the out-of-pocket maximum in a bad year without panic.
- Like your local doctors and they’re in the plan’s network, and you don’t plan to move or travel much.
- Value the extras. If you’d otherwise pay out of pocket for dental work, glasses, or hearing aids, those benefits have real dollar value. Just check the limits; many plans cap dental coverage at a modest amount.
- Qualify for extra help. If your income is low, you may qualify for a Special Needs Plan or programs that make Medicare Advantage especially affordable.
7 Money-Saving Moves to Make Before December 7
Whichever path you’re on, use this Open Enrollment window to make sure you’re not overpaying.
- Read your Annual Notice of Change. If you’re in a Medicare Advantage or Part D plan, this letter tells you exactly what’s changing next year: premiums, copays, the drug list, and the out-of-pocket maximum. Don’t toss it.
- Check that your doctors are still in-network. Networks change. Call your doctor’s office directly and ask, “Will you be in-network with this plan in 2027?”
- Run your exact prescriptions through the plan finder. The Medicare Plan Finder lets you enter your drugs and pharmacy to compare true yearly costs, not just premiums. Plans that look cheap can cost more once your medications are added.
- Compare the out-of-pocket maximum, not just the premium. A plan with a $0 premium and a $9,850 maximum may be riskier than a plan with a $30 premium and a $4,500 maximum.
- Shop your Medigap premium. If you already have Medigap and are healthy or live in a birthday-rule state, get quotes. The same Plan G can vary by hundreds of dollars a year between companies, for identical coverage.
- Get free, unbiased help. Every state has a State Health Insurance Assistance Program (SHIP) with trained counselors who don’t sell anything. It’s one of the best-kept secrets in retirement.
- Watch out for high-pressure sales. Be careful with anyone who calls you unexpectedly, claims to be “from Medicare,” or pushes you to decide on the spot. Medicare will not cold-call you to sell a plan. Report suspicious calls to Medicare’s fraud line.
Health coverage is one of the largest expenses after 60, but it’s not the only place to save. How to Save on Health Insurance Premiums in Retirement covers more ways to lower what you pay for coverage each year.
You Need a Winning Strategy
When it comes to navigating the ocean of resources for older adults, it helps – a lot – to have someone who can show you the way. Book a call with a coach to save time, money, and no small amount of frustration.
Click Here to Book a CallA Note on Your Income: Don’t Let IRMAA Surprise You
If your income is higher, you may pay more for both Part B and Part D through an extra charge called IRMAA (Income-Related Monthly Adjustment Amount). It’s based on your tax return from two years earlier, so a big Roth conversion, home sale, or required withdrawal in 2025 can raise your Medicare premiums in 2027.
IRMAA applies whether you choose Medigap or Medicare Advantage, so it shouldn’t change your decision. But it should affect how you plan withdrawals and big sales. If your income dropped because you retired, you can ask Social Security to recalculate using Form SSA-44.
Speaking of Social Security, the 3.6% cost-of-living adjustment for 2027 will add roughly $75 a month to the average check. Some of that raise will go toward a higher Part B premium, which is one more reason to make sure every other healthcare dollar works as hard as possible.
Pick the Plan That Protects Your Cash (and Your Freedom)
There’s no single “best” Medicare choice, only the best choice for your health, your savings, and your stomach for risk. If you want to maximize monthly cash flow today and you’re healthy with a solid emergency fund, Medicare Advantage can save you thousands, especially in your 60s. If you want to protect your nest egg for the long haul, sleep well at night, and keep the freedom to see any doctor, Medigap usually wins over a full retirement, especially if you lock it in while you still qualify without health questions.
Either way, don’t let a TV ad, a mailer, or a pushy caller make this decision for you. Run your real numbers, check your doctors and prescriptions, talk to a free SHIP counselor, and make your choice before December 7. A few hours of homework now can protect tens of thousands of dollars of your retirement money, and that’s money you can spend on living your best life after 60.
This article is for educational purposes and isn’t personalized insurance or financial advice. Medicare costs and rules change every year; confirm current figures at Medicare.gov or with a licensed, unbiased advisor before you decide.
